

Sanusi Admits Blocking Telcos From Banking Was Wrong
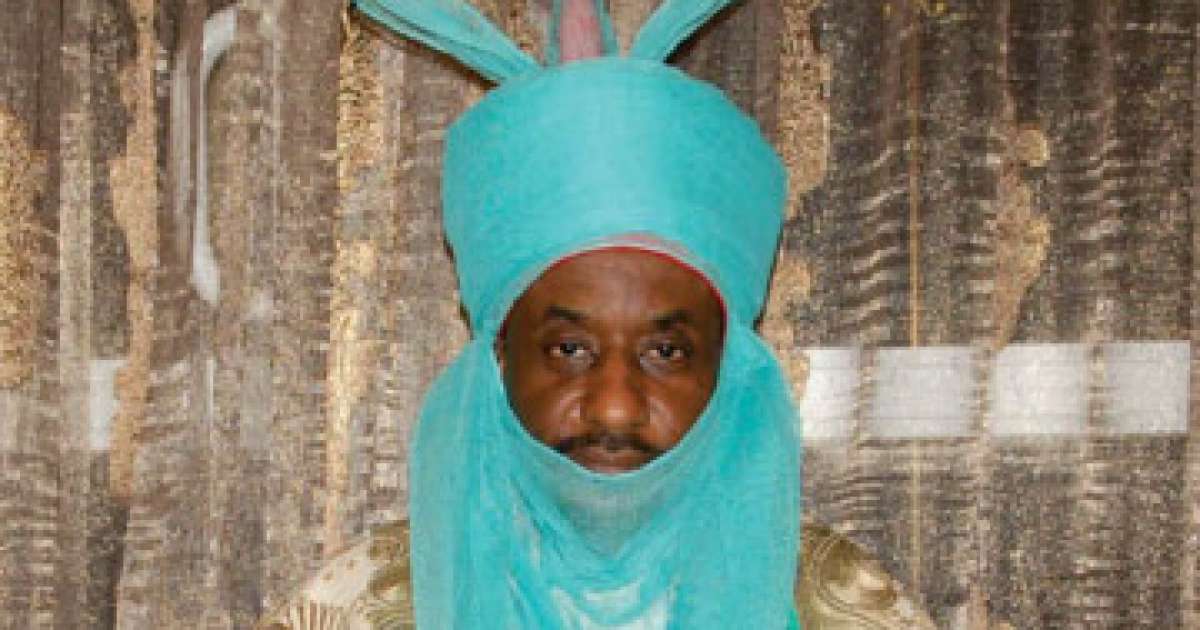
Former Governor of the Central Bank of Nigeria and Emir of Kano, Muhammadu Sanusi II, has admitted that his decision to delay the entry of telecommunications companies into Nigeria’s financial services industry while at the apex bank was a mistake that slowed the country’s financial inclusion drive.
Sanusi said his opposition at the time stemmed from concerns about the safety of depositors’ funds following the banking crisis, but acknowledged that subsequent developments showed the importance of telecommunications and technology companies in extending financial services to underserved Nigerians.
He made the admission on Wednesday during a fireside chat at the official launch of the Access to Financial Services in Nigeria 2026 Survey Report in Abuja.
The discussion was moderated by the Dean of Lagos Business School, Prof. Olayinka David-West.
Looking back on decisions taken during his tenure as CBN governor between 2009 and 2014, Sanusi said, “I’m responsible for delaying the entry of telcos into this space.”
He explained that the decision came shortly after Nigeria had emerged from a banking crisis, when regulators were particularly concerned about protecting depositors.
“Part of the challenge, of course, was that we had just come out of a banking crisis where we were worried about depositors’ funds. And I wasn’t comfortable allowing companies that I was not a primary regulator of to have access to a huge pool of funds,” he said.
Sanusi, however, acknowledged that the concern, while well-intentioned, resulted in a policy decision he now considers wrong.
“So again, this is one case where you have a good intention, but you take a wrong decision,” he said.
The former CBN governor recalled that he strongly resisted calls from institutions and other stakeholders to open the financial services space more quickly to telecommunications companies.
“I fought the World Bank. I fought everybody,” Sanusi said, adding that allowing telcos into the sector earlier could have accelerated Nigeria’s progress in bringing millions of unbanked citizens into the formal financial system.
“I do think if I had allowed that to happen, it would have been much more progress,” he said.
According to him, the expansion of technology-driven financial services in recent years has demonstrated the limitations of relying largely on traditional banks to deepen financial inclusion.
“I think we made more progress in the last few years than we did in the first one, because the banks simply don’t have the boots on the ground. They don’t have the footprint,” he said.
Sanusi’s remarks came as the 2026 Access to Financial Services survey showed further improvement in Nigeria’s financial inclusion indicators, although substantial gaps remain across income groups, gender and geographical locations.
The survey showed that overall financial inclusion increased to 79 per cent in 2026, while the financially excluded population fell to 21 per cent. Formal financial inclusion rose to 73 per cent from 64 per cent recorded in 2023.
Reflecting on the progress, Sanusi said financial inclusion was one of the policy initiatives that had maintained momentum despite changes in leadership and economic policy.
He nevertheless warned that expanding access to bank accounts and digital payments should not be confused with improvements in incomes or economic welfare.
“Opening an account, moving money, is not the same as earning money. It’s not the same as talking about poverty,” he said.
He argued that financial services must be connected more closely to productive activities in the real economy, including agriculture, manufacturing and trade.
According to him, the rise of fintech companies and other digital financial service providers offers an opportunity to connect financial flows with the movement of goods and services from farmers to markets and manufacturers.
Sanusi also called for the existing digital payments infrastructure to be used to expand access to savings, pensions and insurance.
He said that if he were leading the CBN today, he would bring major digital financial service providers together and challenge them to build pension and savings products around the vast transaction data and networks they already possess.
He suggested that small amounts could be accumulated from transactions over time to help informal-sector workers build savings, insurance and pension buffers rather than requiring large periodic contributions.
Sanusi also urged the CBN to remain focused on price stability, describing inflation as one of the biggest threats to household savings and wealth.
“There is no enemy to savings, no enemy to wealth that is bigger than inflation,” he said.
According to him, the apex bank must resist pressure to abandon tight monetary policy prematurely because sustainable savings and household financial resilience depend partly on bringing inflation under control.
The former CBN governor also reflected on the introduction of a unified identification system for bank customers, saying Nigeria’s financial infrastructure provided a foundation on which credit, insurance, pensions and other services could be built.
He recalled resistance to the idea of establishing a single identification framework across the banking industry rather than allowing individual banks to maintain separate systems.
Sanusi said Nigeria now had the infrastructure to deepen inclusion, but policymakers must focus on translating financial access into economic opportunity.
He further warned against fragmented regulation of consumer protection in financial services, arguing that overlapping responsibilities among regulators could confuse consumers and undermine trust.
According to him, consumer complaints involving banks and other regulated financial institutions require clearly defined lines of responsibility among the CBN, the Federal Competition and Consumer Protection Commission and other sector regulators.
“Consumer protection is so critical to financial inclusion that once you begin to fragment and there isn’t one point of call, there is an issue,” Sanusi said.